
PTIR Expected Move
The expected move for GraniteShares 2x Long PLTR Daily ETF (PTIR) options expiring Nov 20, 2026 (7 DTE) is ±$1.57 (±9.6%), a range of $14.73 to $17.87.
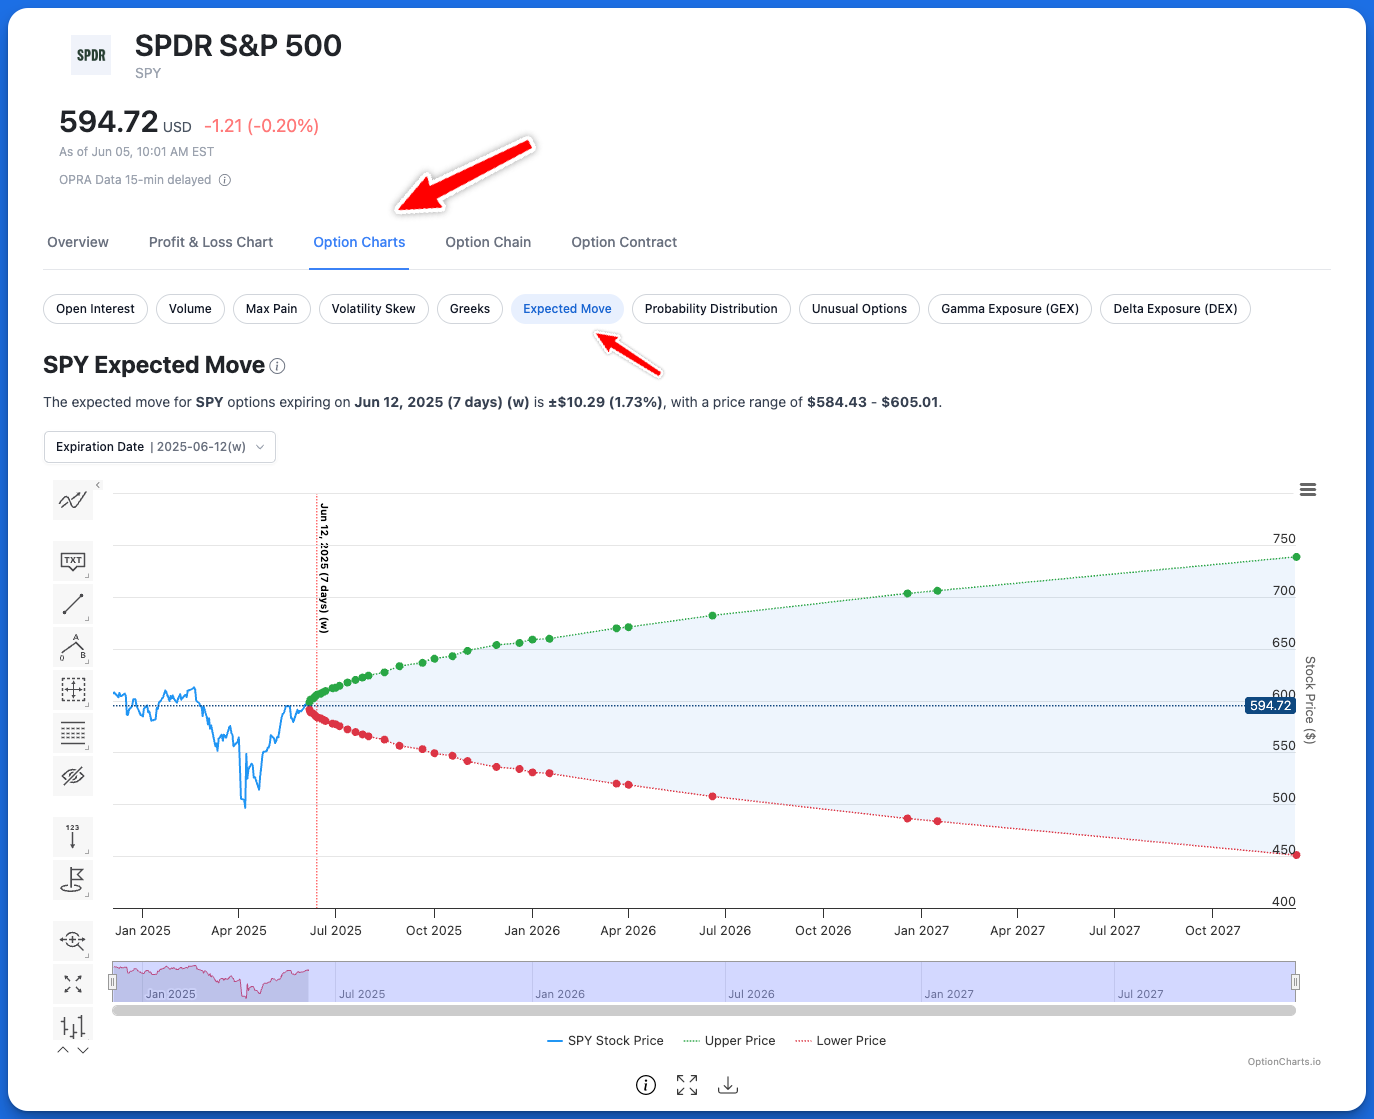
PTIR Expected Move by Expiry
The expected move for all expiration dates of PTIR.
| Expiration | Expected Move ($) | Expected Move (%) | Lower Price | Upper Price | Implied Volatility |
|---|---|---|---|---|---|
| Nov 20, 2026 7 DTE monthly | ±$1.57 | ±9.62% | $14.73 | $17.87 | 109.63% |
| Dec 18, 2026 35 DTE monthly | ±$3.59 | ±22.06% | $12.71 | $19.90 | 103.33% |
| Jan 15, 2027 63 DTE monthly | ±$4.84 | ±29.69% | $11.46 | $21.14 | 100.16% |
| Apr 16, 2027 154 DTE monthly | ±$7.95 | ±48.79% | $8.35 | $24.25 | 103.38% |
| Jan 21, 2028 434 DTE monthly | ±$13.27 | ±81.41% | $3.03 | $29.57 | 105.43% |
| Jan 19, 2029 798 DTE monthly | ±$17.51 | ±107.45% | $-1.21 | $33.82 | 114.06% |
Click row to show expected move chart for that expiration
PTIR Expected Move FAQ
What is an expected move?
The expected move is the price range that option prices imply by a given date, usually one standard deviation. The stock is expected to finish inside that range about 68% of the time.
What is PTIR's expected move this week?
As of Nov 13, 2026, the expected move for PTIR options expiring Friday, Nov 20, 2026 is ±$1.57 (±9.6%), a range of $14.73 to $17.87. The table above shows the current expected move for every expiration date.
How has PTIR implied volatility changed recently?
PTIR 30-day implied volatility went from 114.0% on Oct 15, 2026 to 98.1% on Nov 12, 2026. See the PTIR implied volatility history for a longer view.